Seismic work promises to open new offshore exploration possibilities up and down the coast of West and South Africa. Companies are actively conducting evaluation programs and planning new drilling in multiple basins.
For now, the South African area offshore Namibia and Angola remains the region’s premier hotspot, producing the most notable exploration successes. But other prospective areas offshore West Africa look to be just one major discovery away from breakout.
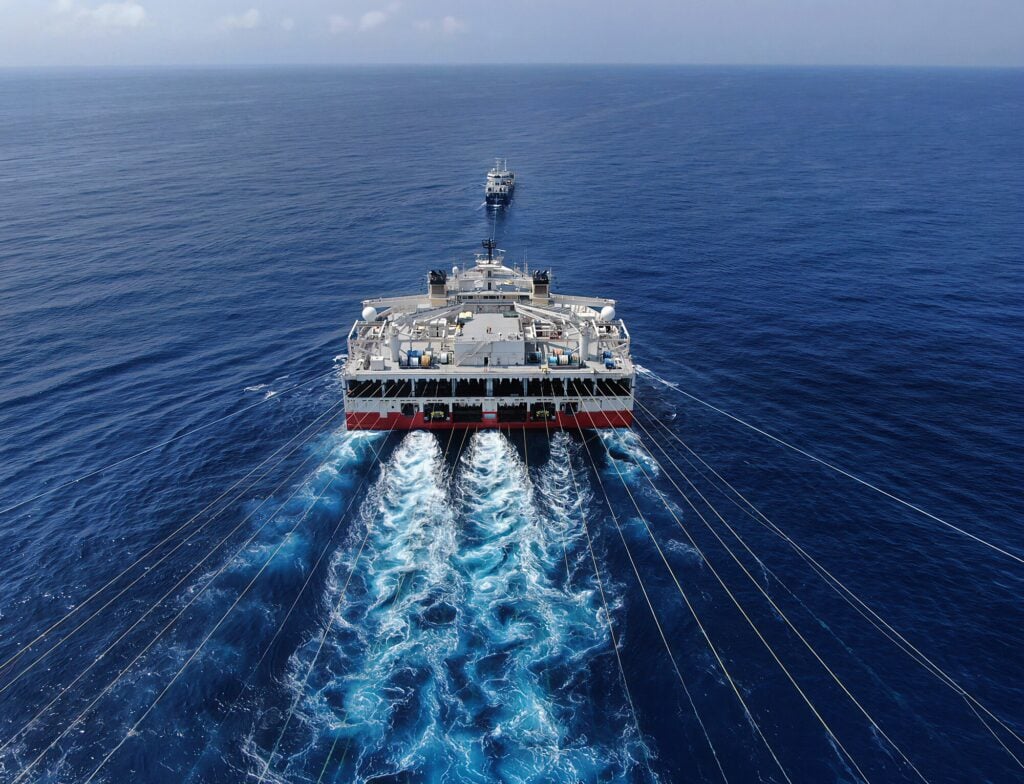
Geophysics drives evaluation efforts off Africa’s west coast today, and global seismic provider TGS is performing much of that work.
“TGS sees offshore West Africa as a region with significant remaining exploration potential across both established and frontier basin,” said Rob Holden, TGS vice president, Africa, Mediterranean and Middle East, Multi-Client.
“Ultimately, our strategy is about de-risking before block award,” Holden said.
“Our strategy is built around three key areas – partnership, data and technology. Strong partnerships with governments and regulators are increasingly important,” and TGS is an adviser to more than 30 governments on the African continent, he noted.
Seismic programs in the West Africa offshore region often use a multiclient model. Reprocessing of previously acquired data is common.
“The pace of technological development means we can continually improve the value of both new and existing datasets, giving explorers a clearer understanding of increasingly complex geological opportunities in the Atlantic Margin,” Holden said.
TGS invests heavily in advancements of geophysical technology, he said, including “the next generation of GeoStreamer broadband streamers, streaming vast amounts of data in hours from the vessel into our imaging center via high-capacity cloud and LEO (low Earth orbit) satellites” and “differentiating Gemini extended-frequency source technology that continues to grow in demand.”
From Discovery to Licensing
In recent exploration results, Chevron subsidiary Cabinda Gulf Oil Company Ltd. confirmed an oil and gas condensate discovery in Block 0 offshore Angola in August. Its 105-4X well in the Lower Congo Basin found a hydrocarbon column of more than 600 meters in the primary Pinda reservoir, with more than 90 meters of net pay.
“I would describe it as excellent pay,” said Kevin McLachlan, Chevron vice president of exploration.
“The early results are encouraging, and additional work will help determine the resource’s full potential and possible development opportunities,” he added.
Cabinda operates the block with a 39.2-percent interest. Sonangol E&P holds the largest working interest in the block at 41 percent, Chevron noted, while TotalEnergies and Azule Energy are also partners.
To the south, offshore Namibia, Chevron reported preparations for a new multi-well exploration program. Drilling plans include the high-impact Nabba-1X exploration well on license block PEL90, expected to spud before year-end.
ExxonMobil made an oil and gas discovery offshore Angola in Block 15, its 20th in the block over the past 30 years. Its Vicango East-01 well found about 82 feet of hydrocarbon column in high-quality sandstone, the company reported in September.
Holden said licensing activity, availability of exploration capital, commodity-price expectations and the industry’s continued focus on capital discipline are all influencing the timing and level of seismic investment in Africa.
“The licensing landscape is probably one of the most significant factors affecting seismic investment in the region. West Africa has a wide range of mechanisms for accessing acreage, from conventional licensing rounds and open-door systems to direct negotiations, farm-ins, MoUs (memoranda of understanding) and reconnaissance licenses,” he said.
A reconnaissance license gives an operator or other company the legal right to assess large offshore areas for oil, natural gas and minerals before licensing an exploration block and commencing drilling.
“Each creates a different level of certainty around acreage, timing and ultimately the requirement for seismic data. In particular, the growth of MoUs and reconnaissance licenses can create a disconnect between gaining access to an area and reaching a point where meaningful exploration or licensing commitments are made,” Holden said.
“These mechanisms can be useful for governments and companies in evaluating opportunities – as we’ve seen in Angola, Gabon, Sierra Leone, to name a few – but where licensing decisions and exploration commitments are deferred, they can also defer the seismic investment that traditionally follows,” he noted.
That disconnect or lag can be a quandary for the industry. Geophysical companies often are asked to make significant upfront investments in data to support de-risking, even as “the timing and certainty of the eventual licensing and exploration activity remains unclear,” Holden said.
“Alongside licensing uncertainty, exploration capital discipline, commodity-price expectations, access to infrastructure and the increasing complexity of frontier plays all influence the timing and scale of seismic activity,” he said.
Hot Spots
Beyond Namibia and Angola, here’s a look at other activity offshore Africa, from the northwest corner down:
Morocco: In this region, part of North Africa, recent offshore activity has been limited – primarily because earlier exploration attempts produced mostly dry holes and the Morocco-Western Sahara situation is a political mess.
Murphy Oil has listed offshore Morocco as one of its four exploration focus areas, although the area is under seismic evaluation and no drilling plans had been announced as of September. Murphy has an agreement to operate Morocco’s Gharb Deep Offshore deepwater block with a 75 percent working interest. That block covers more than 4 million acres, it reported.
MSGBC Basin: The area contains several prospective plays and numerous oil and gas discoveries made during the past decade. It includes and gets its name from offshore areas of Mauritania, Senegal, The Gambia, Guinea-Bissau and Conakry, the capital of Guinea.
Late last year, geophysics giant TGS launched its Mauritania MegaSurvey, a multiclient 3-D seismic project offshore Mauritania and extending to the wider West African Atlantic Margin. The survey comprises more than 100,000 contiguous square kilometers of modern seismic data, TGS reported.
Seismic provider Viridien signed a multiclient partnership agreement with Petrosen, Senegal’s national petroleum company, in August. It described the agreement as creating “a collaborative framework for Viridien to deliver comprehensive subsurface intelligence throughout the prolific and highly prospective MSGBC Basin.”
In September, Petrosen reportedly entered a memorandum of understanding with Eni to evaluate the potential of five specific blocks offshore Senegal. Under the MOU, Eni will pay for and conduct technical studies to analyze blocks SN01M, SN02M, SN03M, SN07M and SN40M. The country eventually plans to offer up to 109 oil and gas blocks, according to its energy minister.
A Chevron subsidiary acquired exploration blocks 5B and 6B offshore Guinea-Bissau with a 90-percent interest last year, then added block 4B in August. The company is leveraging legacy 2-D seismic data and 3-D surveys acquired in the area in 2017 and 2018.
West African Transform Margin: The transform margin stretches from Sierra Leone and Liberia to offshore western Nigeria and includes Ghana’s offshore Jubilee Field. According to TGS, “the region’s proven Upper Cretaceous reservoirs and prolific source rocks highlight its potential, particularly within basins like the Tano Basin, which have demonstrated consistent productivity.”
Early this summer, TGS began its Sierra Leone 2-D and Mabesi 3-D Vision reprocessing projects offshore Sierra Leone, supporting early-stage evaluation and target prioritization. The program includes the reprocessing of 24,000 kilometers of 2-D field data from multiple input surveys and 4,155 square kilometers of Mabesi 3-D seismic data through comprehensive pre-stack depth migration.
The Mabesi 3-D Vision project also will be merged with additional, recently completed reprocessing, with final results projected in the first quarter of 2027. Final products from the Sierra Leone 2-D Vision work are expected in the second half of next year.
Liberia: TotalEnergies has evaluation and seismic programs ongoing in two areas offshore Liberia. Last year it signed production sharing contracts for blocks LB-6, LB-11, LB-17 and LB-29 covering about 12,700 square kilometers in the south Liberia Basin, with a program that includes acquisition of a 3-D seismic survey.
With Canadian explorer BluEnergies, it’s also carrying out a joint study of a deepwater fan play in blocks LB-26, LB-30 and LB-31 in the Harper Basin. Work includes reprocessing by TGS of almost 6,200 square kilometers of 3-D seismic acquired in 2013, plus new sea-bottom data acquisition.
Côte d’Ivoire: Viridien is conducting an ongoing subsurface reimaging program offshore Côte d’Ivoire. Earlier this year it began phase CDI25, a 6,555-square-kilometer seismic reimaging project in the Tano Basin. Upon completion, Viridien reported, “the overall reimaging program will deliver a seamless, basin-scale 3-D seismic volume providing over 16,000 square kilometers of coverage” over several Tano Basin blocks.
Recent discoveries in the basin include the Calao South/Murene South gas and condensate find by Eni and Murphy Oil’s oil discovery with the Bubale-1X exploration well in Block CI-709.
Ghana: In a 3-D-from-2-D effort, TGS is developing a Gulf of Guinea 2-D-cubed project across Ghana’s lightly explored offshore Keta Basin. For Phase 1, it plans to combine 5,500 square kilometers of 3-D data and more than 14,700 kilometers of 2-D data in a 25,300-square kilometer project covering the basin’s shelf and deepwater areas.
According to TGS, 2-D-cubed technology “generates a single, structural conformable 3-D seismic volume from existing datasets through use of an interpolation workflow to fill the gaps between lines and to suppress legacy migration artefacts.”
Nigeria: TGS announced its Nigeria Laide multiclient 3-D survey earlier this year, in partnership with the Nigerian Upstream Petroleum Regulatory Commission. The survey, within the Outer Fold and Thrust Belt of the eastern Niger Delta, covers about 11,700 square kilometers.
Shearwater Geoservices has completed a 3-D marine seismic survey for TotalEnergies EP Nigeria and Matrix Energy on blocks OML 100 and OPL 2010 offshore Nigeria. It reported finishing the survey in May.
Equatorial Guinea: The Central African country moved away from a planned bid round for 2026 and now offers multiple exploration blocks, including offshore blocks, through direct negotiation.
Geophysical company Searcher concluded its Equatorial Guinea 2-D Reprocessing Project in March. The program comprised 7,337 kilometers of regional offshore 2-D seismic data from two input surveys.
In June, TGS announced it had signed an agreement with the Ministry of Hydrocarbon and Mining Development to create a large-scale, multiclient seismic project. The first phase will include post-stack reprocessing of about 27,273 kilometers of 2-D seismic data and around 35,000 square kilometers of 3-D seismic data. The project will support exploration risk reduction across the Rio del Rey and Rio Muni basins, TGS noted.
São Tomé and Príncipe: Going for re-reprocessing, TGS commenced its São Tomé and Príncipe 2-D PSDM Reprocessing project in August. The program covers 14,651 kilometers of 2-D seismic data acquired between 1999 and 2005. That data was previously reprocessed by TGS in 2014.
The company noted, “Offshore São Tomé and Príncipe presents a demanding subsurface environment, with volcanic activity, shallow channelization and pervasive mass transport complexes historically limiting the clarity of legacy seismic imaging and depth positioning of targets. The 2-D PSDM Reprocessing project is designed to resolve these specific challenges.”